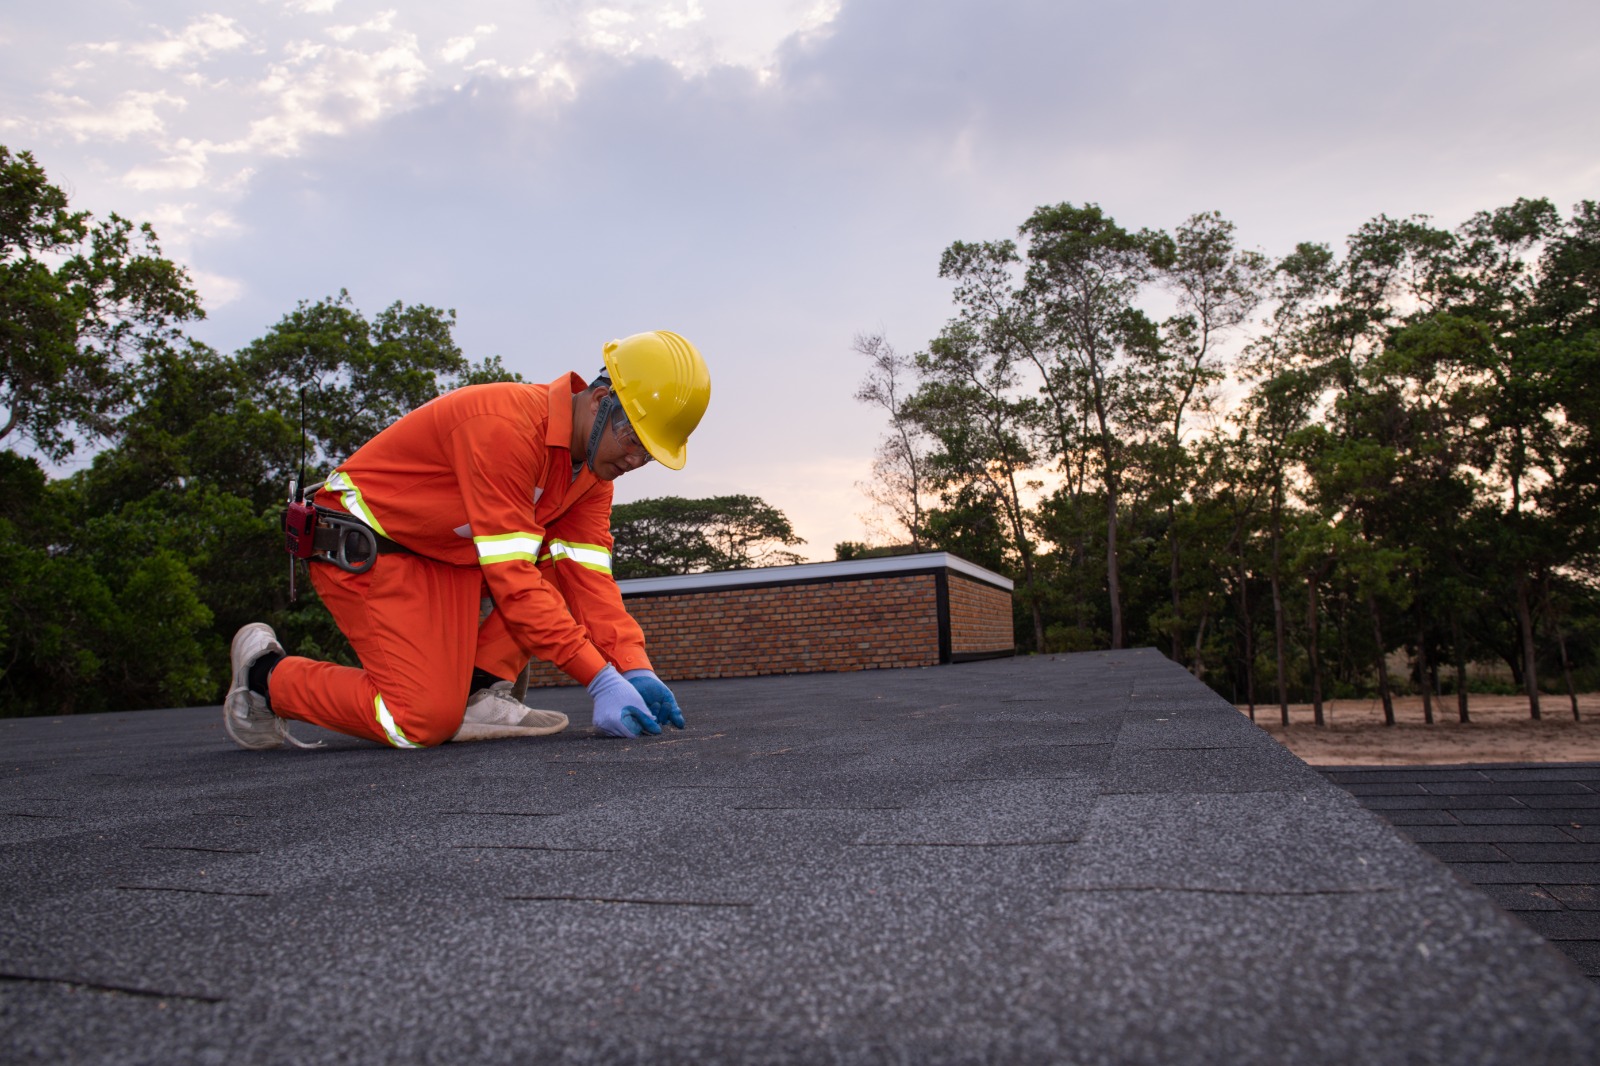
If you own a home in Orlando, your insurance agent may have asked for a “wind mit”, or you may have heard that one can cut the hurricane portion of your premium. A wind mitigation inspection is a short, standardized check of how well the house is built to resist wind, recorded on a state form. This guide explains what the inspection looks at, who can sign the form, how long it is valid, and how it differs from a 4-point inspection.
What is a wind mitigation inspection?
It is an inspection that records the wind-resistant features of a house on Florida’s Uniform Mitigation Verification Inspection Form, OIR-B1-1802. Insurers use the form to decide which wind mitigation credits or discounts apply to the hurricane portion of a homeowners policy. The inspector answers seven questions, backed by photographs and documents.
The form itself is adopted by rule 69O-170.0155 and published by the Florida Office of Insurance Regulation. It tells the homeowner to keep a copy with the insurance policy, and says that the insurer may ask additional questions about the features verified on it.
The legal basis for the discounts is section 627.0629 of the Florida Statutes. It requires residential property insurance rate filings to include actuarially reasonable discounts, credits, other rate differentials or reductions in deductibles for homes with features shown to reduce windstorm losses, and it names roof strength, roof covering performance, roof-to-wall strength and opening protection among them.
What does a wind mitigation inspection cover?
Seven items on the OIR-B1-1802 form: the building code the house was built to, the roof covering, roof deck attachment, roof-to-wall attachment, roof geometry, secondary water resistance and opening protection. Most of them concern the roof. Each answer must be supported, and at least one photograph is required for each attribute in questions 3 to 7.
| Question | What the inspector records |
|---|---|
| 1. Building code | Whether the house was built to the Florida Building Code (2001 or later), with a permit application date for homes built in 2002 or 2003 |
| 2. Roof covering | Each roof covering type, with its permit date, product approval number or year installed |
| 3. Roof deck attachment | The weakest way the roof sheathing is fastened to the trusses or rafters |
| 4. Roof-to-wall attachment | The weakest connection between the roof framing and the walls: toe nails, clips, single wraps, double wraps or structural |
| 5. Roof geometry | Hip roof, flat roof or other |
| 6. Secondary water resistance | Whether a sealed roof deck is present |
| 7. Opening protection | Protection of windows, doors and other openings |
Because the form records the weakest attachment, not the best, a house with a few weak connections is graded on those. The inspector needs attic access for the deck and roof-to-wall questions; the form has “no attic access” as an answer for both, and an unknown answer cannot earn a credit.
What do the roof questions on the form mean?
They describe how the roof is fastened and protected. Roof deck attachment grades the nailing of the sheathing; roof-to-wall attachment grades the metal connectors tying the roof to the walls; roof geometry rewards hip roofs; and secondary water resistance records a sealed deck that keeps water out if the roof covering is lost.
In plain terms, from the form’s definitions:
- Roof deck attachment. Option A is sheathing fastened by staples or 6d nails at 6 inches on the edge and 12 inches in the field. Options B and C are 7/16-inch or thicker sheathing with 8d common nails at a maximum of 12 or 6 inches in the field.
- Roof-to-wall attachment. Toe nails are the lowest category. Clips, single wraps and double wraps are metal connectors, which must have at least three nails, sit tight to the framing and be free of visible severe corrosion to count.
- Roof geometry. A hip roof qualifies when other roof shapes make up no more than 10 percent of the total roof perimeter.
- Secondary water resistance. Self-adhering polymer modified-bitumen underlayment applied directly to the sheathing, or a foam adhesive barrier. Standard underlayment or hot-mopped felt does not qualify.
These are the features a re-roof can change. Re-nailing the deck and adding a sealed roof deck are done while the old roof is off, which is why a new roof is a natural time to have the house re-inspected.
Who can do a wind mitigation inspection in Florida?
Only the qualified inspectors listed on the form. They are licensed home inspectors who have completed approved hurricane mitigation training and a proficiency exam, certified building code inspectors, licensed general, building or residential contractors, professional engineers, professional architects, or others the insurer recognizes as qualified.
The form sets out the detail:
| Inspector | Licensing basis on the form |
|---|---|
| Home inspector | Licensed under section 468.8314, with approved hurricane mitigation training and a proficiency exam |
| Building code inspector | Certified under section 468.607 |
| General, building or residential contractor | Licensed under section 489.111 |
| Professional engineer | Licensed under section 471.015 |
| Professional architect | Licensed under section 481.213 |
| Other | An individual or entity the insurer recognizes as qualified under section 627.711(2) |
Inspectors other than licensed contractors and engineers must inspect the house personally. Contractors and engineers licensed under those sections may have a direct employee do the inspection, but they sign for the work. That answers the question of whether a general contractor can do one: yes, if licensed under section 489.111.
How long is a wind mitigation inspection good for in Florida?
Up to five years. The OIR-B1-1802 form states that it is valid for up to five years, provided no material changes have been made to the structure and no inaccuracies are found on the form. A re-roof or new shutters are material changes, so a fresh inspection can record the improvements.
That five-year window is a reason to keep your copy safe. If you change insurers within it, the same form can be provided again, and the insurer may still ask its own questions about the features verified.
After a re-roof, ask for a new inspection rather than relying on an old form. The old one describes the old roof, including its deck attachment and underlayment, and will not show improvements such as a sealed roof deck or upgraded nailing.
How do you get a free wind mitigation inspection in Florida?
Through the My Safe Florida Home program, when it is accepting applications. The state program offers free wind mitigation inspections to eligible homeowners, and the inspection report can be shared with the insurer and used as a roadmap for retrofits. Eligibility and funding are set by the program, so check its site.
The My Safe Florida Home program describes two benefits of its inspection report: you can share it with your insurance carrier to make sure you are receiving the available discounts on the hurricane portion of your premium, and it is a roadmap to retrofitting your home against hurricanes. The program also offers grants for approved upgrades to eligible homeowners.
Program details, including eligibility, application windows and grant amounts, change over time. Read the current terms on the program’s own site before you rely on them.
How much discount do you get for wind mitigation in Florida?
There is no single percentage. Discounts and credits are part of each insurer’s filed rates, which the Office of Insurance Regulation reviews under section 627.0629. The amount depends on your insurer, your policy and which features the form verifies, so ask your agent to show the credits applied before and after.
The statute requires the discounts to be actuarially reasonable and to apply to features shown to reduce windstorm loss. It also says credits must be included for fixtures and construction techniques that meet the minimum requirements of the Florida Building Code.
Questions worth asking your agent:
- Which credits are on my policy now? And which form answers they are based on.
- What would change if the roof deck attachment, roof-to-wall attachment or secondary water resistance answers improved.
- Does the credit apply to the hurricane portion of the premium or the deductible.
Is a 4-point inspection the same as wind mitigation?
No. A wind mitigation inspection records features that resist wind damage and can earn discounts. A 4-point inspection is an insurability check of four systems: the roof, electrical, plumbing, and heating and air conditioning. Insurers may ask for one on older homes before writing or renewing a policy.
Citizens Property Insurance publishes a sample 4-Point Inspection Form that sets out the difference clearly. It must be completed and signed by a Florida-licensed inspector, and it says the information is used only to determine insurability and is not a warranty of the systems inspected.
| Wind mitigation | 4-point | |
|---|---|---|
| Purpose | Verify wind-resistant features for discounts | Check insurability of four major systems |
| Form | OIR-B1-1802 | Insurer’s form, such as Citizens’ sample |
| Roof focus | Deck nailing, roof-to-wall connectors, shape, sealed deck | Covering, age, remaining useful life, condition |
| Other systems | Openings | Electrical, plumbing, heating and air conditioning |
How do you prepare for a wind mitigation inspection?
Gather paperwork and clear access. The inspector needs permit dates or product approval numbers for the roof covering, any paperwork for shutters or impact windows, and a clear path into the attic. Without attic access, the deck and roof-to-wall questions may be marked unknown and earn no credit.
A short checklist:
- Roof permit. The permit application date for the current roof, if you have it.
- Product approvals. For the roof covering, windows, doors and shutters.
- Re-roof paperwork. Invoices or documents showing deck re-nailing or a sealed roof deck.
- Attic access. Clear the hatch and the area under it.
- Shutters. Have them available so the inspector can see what is installed.
The form says any documentation used to validate a feature must accompany it, so the more paperwork you can provide, the fewer items are left unverified.
Can a new roof improve your wind mitigation report?
It can. Re-roofing to the current code can improve the roof covering, roof deck attachment and secondary water resistance answers on the form, because the deck is exposed and can be re-nailed and sealed. A roof-to-wall connection can sometimes be reached at the same time, depending on the house. A new inspection afterwards records the changes, so the insurer can review the credits against the new answers.
If you are planning a re-roof, Residential Roofing Orlando can explain which roof details on the form a replacement would affect, so you can ask a qualified inspector to verify them afterwards. See our roof inspection service or call (407) 305-0865.
Frequently asked questions
These are short answers to questions homeowners search about wind mitigation inspections. Each points back to a fuller section above. Check the form and your policy for the details that apply to your home.
What is a wind mitigation inspection?
An inspection that records a home’s wind-resistant features on Florida’s OIR-B1-1802 form. The seven questions cover the building code, roof covering, roof deck attachment, roof-to-wall attachment, roof geometry, secondary water resistance and opening protection, and insurers use the form to apply wind mitigation credits.
How long is a wind mitigation inspection good for in Florida?
The OIR-B1-1802 form says it is valid for up to five years, provided no material changes have been made to the structure and no inaccuracies are found. After a re-roof or other upgrade, a new inspection can record the improved features.
Can a general contractor do a wind mitigation inspection in Florida?
Yes. The form lists general, building and residential contractors licensed under section 489.111 as qualified inspectors, along with qualifying home inspectors, building code inspectors, engineers and architects. Contractors and engineers may have a direct employee do the inspection, but they sign and take responsibility for it.
Is a 4-point inspection the same as wind mitigation?
No. Wind mitigation verifies features that reduce wind damage and can earn insurance credits. A 4-point inspection checks the roof, electrical, plumbing and heating and air conditioning to decide whether an older home is insurable, and is done on the insurer’s own form.